What if the biggest hurdle to your business growth in the Emirates isn’t the competition, but a single “rejected” status from a bank compliance officer? For many entrepreneurs, corporate bank account opening across the UAE feels like solving a complex puzzle where the rules change without notice. You’ve likely felt the frustration of opaque requirements, long processing times, or the stress of maintaining high minimum balances that tie up your working capital. It’s a common struggle that can make even the most seasoned investor feel like they’re hitting a wall.
This strategic guide provides a clear roadmap to help you secure a fully operational business bank account with confidence. You’ll gain a deep understanding of current KYC and AML requirements while learning how to present a profile that matches a bank’s specific risk appetite. We’ll explore the essential documentation needed for 2026 and explain how the right support from experts like EBMS Business Services LLC can streamline the entire application process. By the end of this article, you’ll have the insights needed to move from uncertainty to a functional financial foundation for your enterprise.
Key Takeaways
- Understand the mandatory legal documents and the critical role of the Ultimate Beneficial Owner (UBO) declaration in meeting UAE compliance standards.
- Learn why successful corporate bank account opening dubai depends on presenting a business profile that aligns with a bank’s specific risk appetite.
- Evaluate the shift toward digital-first banking options in 2026 and how to select a partner based on your transaction volumes and international trade requirements.
- Discover why the pre-screening phase is the most vital part of the application process for reducing timelines and avoiding common rejection triggers.
- Gain a clear roadmap for navigating the final piece of your company formation journey by leveraging professional documentation reviews to ensure submission readiness.
Navigating Corporate Bank Account Opening in Dubai for 2026
Why do many entrepreneurs find the final step of their setup to be the most demanding? While registering a license is now a streamlined process, corporate bank account opening in Dubai remains a rigorous exercise in compliance. It’s the gateway to the UAE’s transparent financial ecosystem. A business account serves as more than just a place to hold funds; it’s a badge of legitimacy for your operations in a globally recognized market.
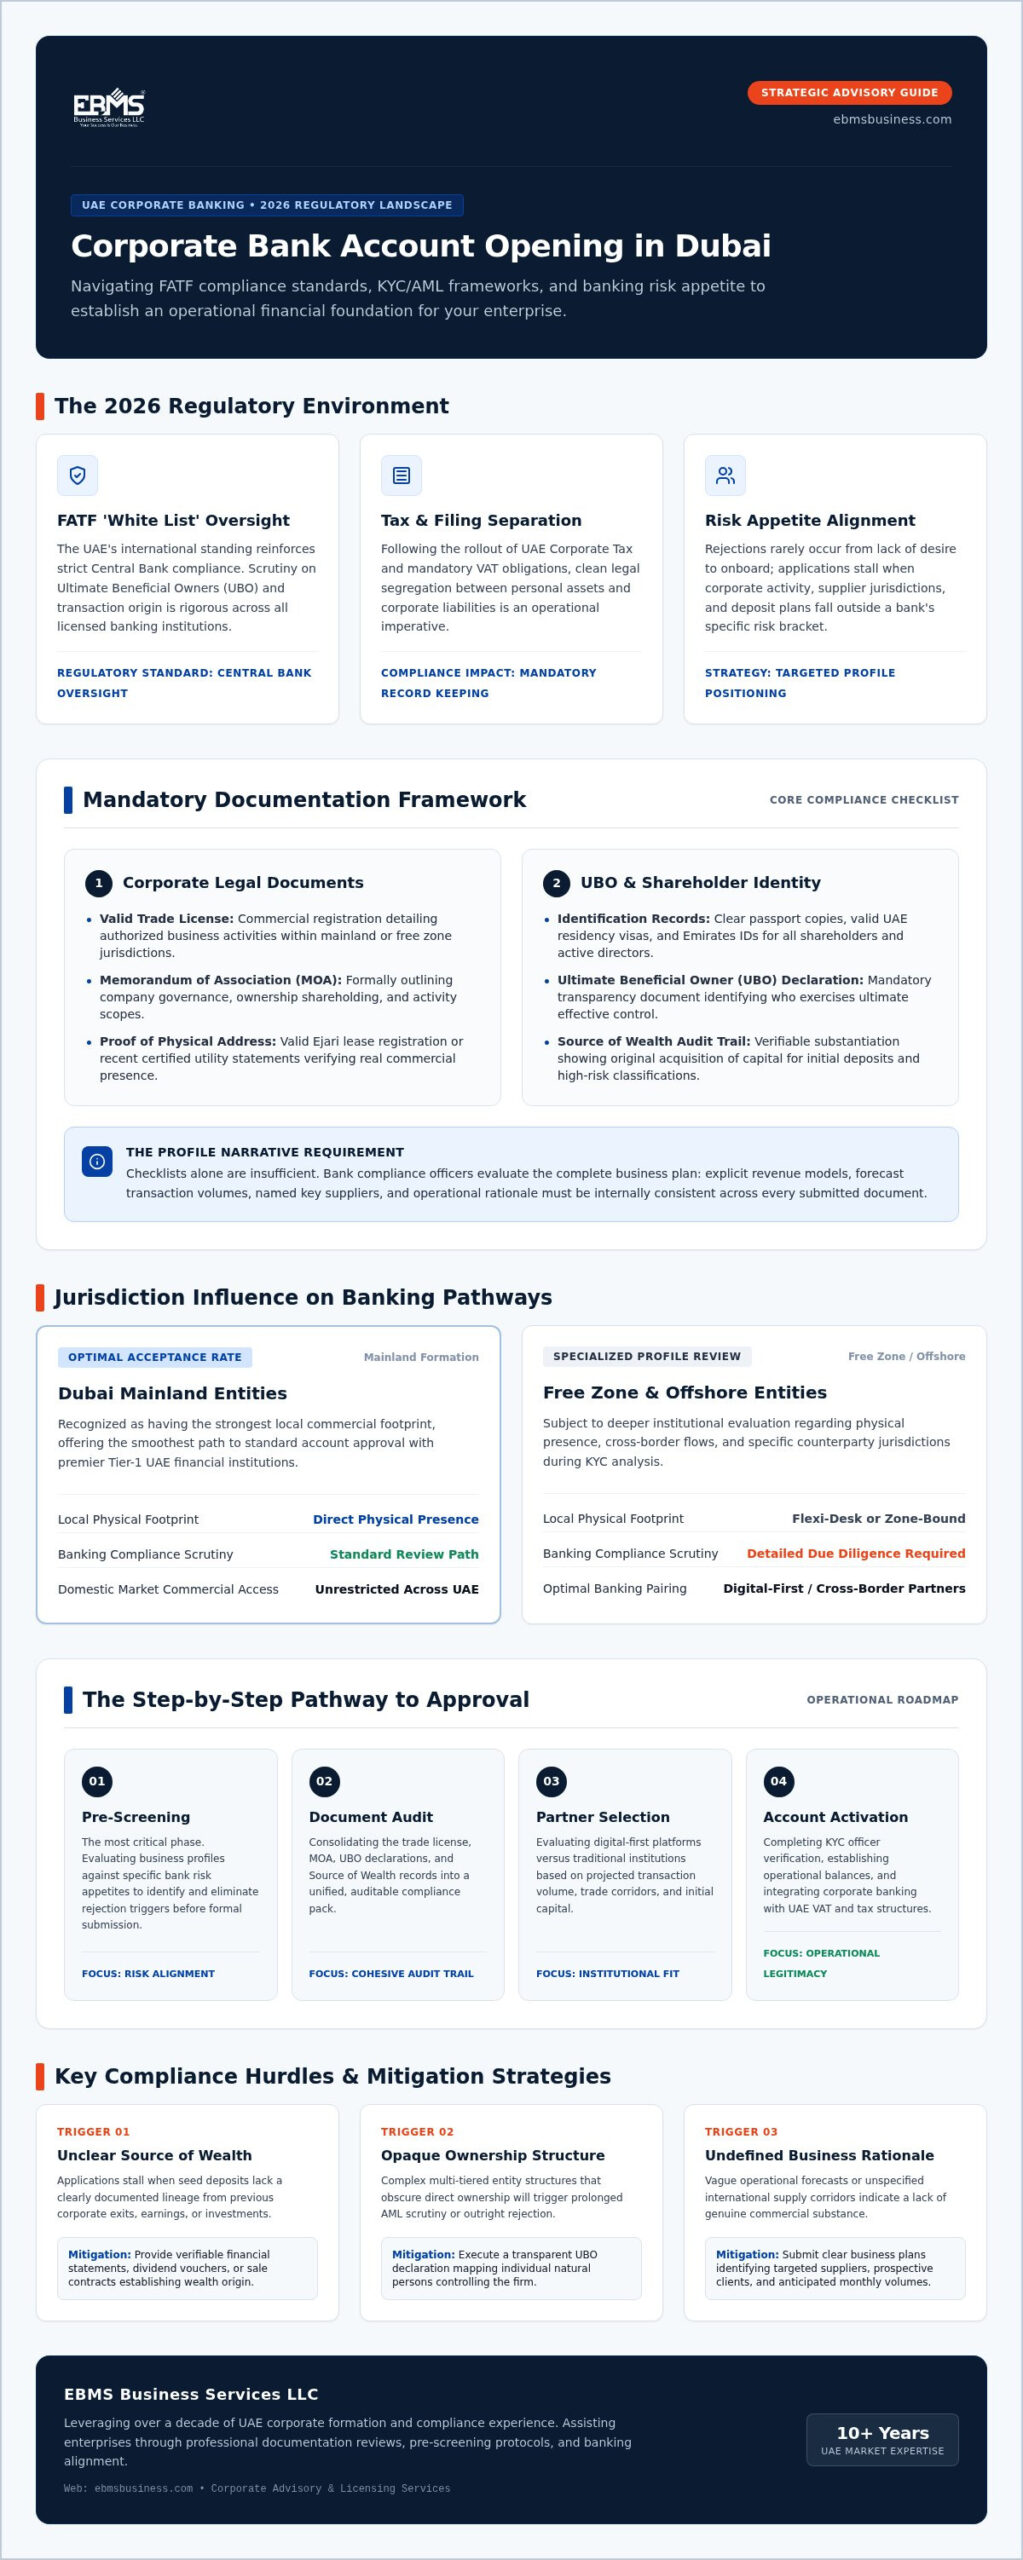
The UAE’s current standing on the FATF ‘White List’ underscores its commitment to international financial standards. This success means the Central Bank of the United Arab Emirates enforces strict oversight on all licensed institutions. For you, this translates to deeper scrutiny during the application phase. EBMS Business Services LLC acts as a vital bridge here, translating these complex regulatory expectations into actionable steps for your business. We leverage over a decade of experience to ensure your profile meets these high standards from the very first submission.
Why a Dedicated Business Account is Essential
Mixing personal and professional finances is a risk you can’t afford. A dedicated account ensures a clear legal separation between your personal assets and business liabilities. This is fundamental for long-term protection and professional credibility. Since the introduction of corporate tax and mandatory VAT filings for qualifying businesses, having a structured banking history is no longer optional. It’s the primary tool for maintaining accurate records and building the financial foundation required for future credit lines or expansion opportunities. Securing a corporate bank account opening in Dubai is the final, critical piece of the business setup puzzle that transforms a license into a functioning entity.
The Regulatory Landscape and AML Compliance
The primary hurdle for most applicants isn’t the bank’s desire to work with you, but the ‘Know Your Customer’ (KYC) requirements. Banks must strictly follow Anti-Money Laundering (AML) and Counter-Terrorism Financing (CTF) protocols. They need to understand exactly where your capital comes from and who the Ultimate Beneficial Owners are. While this process can feel intrusive, it’s the foundation of the UAE’s stable and secure economy. Expert bank account opening in UAE assistance helps you prepare for these inquiries so your first impression with the bank is one of transparency and readiness. By solving the compliance puzzle early, you significantly reduce the risk of facing repeated rejections or long processing delays.
Essential Requirements and Documentation for UAE Banking
Successful corporate bank account opening in dubai isn’t just about having the right papers; it’s about presenting a cohesive narrative to the bank. Why do so many applications fail despite having a valid license? Often, it’s because the documentation doesn’t align with the bank’s specific risk appetite. Central to this is the Ultimate Beneficial Owner (UBO) declaration. Banks must know who ultimately controls the company to prevent financial impropriety. If your business plan doesn’t clearly explain your revenue streams, expected transaction volumes, and key suppliers, the bank’s compliance team may view the application as high-risk. Preparing for corporate bank account opening in dubai requires a proactive approach to compliance that goes beyond a simple checklist.
Standard Documentary Requirements for All Entities
While every bank has its own nuances, the core list of requirements remains consistent across the Emirates. You’ll need a valid Trade License and a Memorandum of Association (MOA) that outlines your business activities. Shareholder and director identification is non-negotiable, requiring passport copies, residency visas, and Emirates IDs. Proof of address is equally critical, usually satisfied by an Ejari or recent utility bills. For high-risk profiles or large initial deposits, a ‘Source of Wealth’ document is mandatory to provide a clear, verifiable audit trail of how the investment capital was originally acquired. For a deeper look at the commercial environment, the International Trade Administration UAE trade financing guide offers a helpful overview of onshore versus offshore operations.
Requirements for Free Zone and Offshore Companies
The path you chose during setup affects your banking journey. Generally, Dubai Mainland company formation offers the smoothest path to banking because mainland entities are seen as having a stronger local footprint. In contrast, companies registered in Meydan Freezone or IFZA might face different levels of scrutiny depending on whether they have a physical office or a flexi-desk. Offshore entities face the highest hurdles, often requiring a Certificate of Incumbency to prove the current standing of directors and shareholders. Resident directors benefit from having a local credit history, while non-residents must provide extensive documentation from their home jurisdiction to satisfy KYC protocols. If this feels overwhelming, you can speak with a consultant to review your file before you approach a bank.
Selecting the Ideal Banking Partner for Your Operations
How do you decide which bank is right for your business? In the UAE, the choice isn’t just about the brand on the building, but about finding a partner whose risk appetite aligns with your specific industry. Some banks excel at supporting high-volume international trade, while others focus on providing streamlined digital tools for consultants. Successful corporate bank account opening in dubai requires you to look beyond the marketing and evaluate the practicalities of daily operations. Banks often specialize; a bank that is perfect for a local retail shop might be highly restrictive for a logistics firm with complex cross-border payments. Assessing this appetite before you apply is the best way to avoid the disappointment of a late-stage rejection.
By 2026, the landscape has shifted significantly toward digital-first business banks. These institutions have removed much of the friction from the application process, yet they might not offer the deep trade finance capabilities required by large-scale importers. It’s a strategic trade-off. You might choose a traditional bank for the prestige and relationship management, or a digital one for the speed and lower overhead. Understanding these nuances is part of the puzzle-solving approach EBMS takes to ensure your banking setup is as efficient as your company formation.
Digital Banks vs. Traditional Institutions
Speed is the primary advantage of digital platforms. For freelancers and small startups, these banks often provide a path to an IBAN in a fraction of the time it takes a legacy institution. If your business requires complex trade finance, physical branch access, or high-value corporate loans, a traditional bank remains the gold standard. These institutions provide dedicated relationship managers who can navigate internal compliance for unique transaction patterns. Choosing the wrong type of partner can lead to operational bottlenecks that stall your growth before it begins.
Comparing Minimum Balance Requirements and Fees
Monthly Average Balance (MAB) tiers are a critical consideration for your cash flow. While you might hear talk of “zero balance” accounts, these are often limited to specific introductory periods or very basic digital tiers. Most corporate accounts in the UAE require a minimum balance ranging from 10,000 د.إ to 50,000 د.إ for standard business accounts, with premium tiers reaching much higher. Failing to maintain this balance results in monthly penalties that quickly add up. Beyond the MAB, you must scrutinize the fee schedule for inward and outward remittances. High transaction fees can quietly erode your margins, especially for businesses with high-frequency international payments. Professional corporate bank account opening dubai assistance helps you compare these costs transparently so you select a partner that supports your bottom line.
The Step-by-Step Process to Account Approval
How long does it actually take to receive your IBAN? While some digital marketing suggests corporate bank account opening in dubai happens in minutes, the reality for most businesses is a methodical progression that requires patience and precision. The journey starts with pre-screening, which we consider the most critical phase of the entire application. If your documents aren’t vetted for compliance before the bank’s internal team sees them, you risk an immediate red flag that can be difficult to clear later. EBMS focuses on this “soft review” to ensure your profile is airtight before the official clock starts ticking.
Expect a realistic timeline of roughly two to four weeks from the initial submission to full account activation. During this window, you’ll enter the ‘Request for Information’ (RFI) phase. This isn’t a sign that your application is failing; it’s a standard part of the modern banking audit. The RFI phase is where many applications stall because entrepreneurs provide vague or incomplete answers. Addressing these queries with specific, documented evidence keeps the momentum moving toward approval. If you’re unsure how to phrase your responses, it’s best to consult with a banking specialist to ensure your answers align with the bank’s expectations.
Common reasons for rejection often stem from mismatched business activities or an unclear source of funds. We help you pre-empt these issues by analyzing your transaction patterns and supplier lists to ensure they fit the bank’s risk profile. By solving these compliance puzzles early, you significantly reduce the risk of a flat rejection.
Initial Application and Pre-Approval Stages
This stage involves submitting a ‘soft copy’ pack for a preliminary review by the bank’s compliance department. It’s your chance to make a strong first impression without the pressure of a final submission. You’ll likely be asked to attend an initial interview with a relationship manager. This isn’t just a casual chat; it’s a formal assessment of your business’s legitimacy and your understanding of your own financial projections. Drafting a professional business profile that answers compliance questions before they’re even asked is the most effective way to secure a green light for the physical signing stage.
Physical Verification and Final Onboarding
Once you pass the initial hurdles, the bank requires the physical presence of all account signatories in the UAE. This is a non-negotiable security measure where you’ll sign the official bank mandates and the Board Resolution. The Board Resolution is the formal document that authorizes the company to open the account and appoints the individuals who will manage it. After this physical meeting, the bank performs its final background checks. Once the compliance team gives the final nod, you’ll receive your account details, activate your online banking portal, and make your initial deposit to bring the account to life.
Solving the Banking Puzzle with EBMS Business Services
Why struggle with the complexities of the UAE financial system when you can have a navigator by your side? Since 2015, EBMS Business Services has acted as a strategic facilitator for entrepreneurs entering the Dubai market. We understand that corporate bank account opening dubai isn’t a transactional process but a relationship-based one. Our decade of experience allows us to identify which banks are currently welcoming specific business activities, saving you from the cycle of application and rejection. We don’t just provide a list of banks; we provide a bridge to a successful approval by matching your business profile with the right institution.
Our approach is grounded in the philosophy of “educate first and promote second.” We believe that transparency is the foundation of trust. By reviewing your business profile through the lens of a bank’s compliance officer, we identify potential hurdles before they become roadblocks. This proactive strategy ensures your venture is positioned for long-term stability and growth within the Emirates. We view banking as the final, critical piece of the business setup puzzle, and we’re committed to helping you solve it with precision and ease.
Professional Assistance in Documentation Preparation
Meticulous compliance checks are the core of our service. We don’t just gather your documents; we audit them. This involves tailoring your business narrative to meet the specific requirements of your chosen banking partner. Whether you’re a mainland startup or a free zone entity, our bank account opening assistance ensures your submission is polished and professional. We help you articulate your revenue streams and supplier relationships in a way that satisfies even the most rigorous KYC protocols. This attention to detail reduces the risk of rejection and builds a foundation of credibility with your relationship manager.
A Supportive Partner for Operational Readiness
Securing your IBAN is a major milestone, but it’s only one part of your operational foundation. We ensure your banking setup integrates seamlessly with other critical requirements to keep your business running smoothly. For instance, our VAT registration services help you maintain the tax compliance that banks often verify during periodic reviews. Additionally, a professional digital presence is increasingly important for bank verification. Our IT services ensure your company’s digital footprint meets the standards expected by UAE financial institutions. If you’re ready to finalize the last piece of your business setup puzzle, you can contact EBMS for a personalized consultation on your corporate banking needs.
Building a Sustainable Financial Foundation in the UAE
Securing a reliable banking partner is the final, essential piece of your business setup journey. As we’ve explored throughout this guide, successful corporate bank account opening dubai in 2026 depends on more than just a valid trade license. It requires a strategic approach to compliance, a clear understanding of UBO requirements, and the ability to match your business narrative with a bank’s specific risk appetite. By prioritizing thorough pre-screening and professional documentation review, you turn a complex administrative hurdle into a manageable step toward operational readiness.
EBMS Business Services has been a trusted navigator for entrepreneurs since 2015. Our team provides deep local banking knowledge and expertise across both Mainland and Free Zone jurisdictions. We pride ourselves on offering transparent, supportive guidance through the compliance maze, ensuring your application is presented in the best possible light. We’re here to help you solve the banking puzzle so you can focus on growing your venture with confidence. Secure your business foundations; contact EBMS for corporate banking assistance today.
Frequently Asked Questions
Can I open a corporate bank account in Dubai without a residency visa?
Yes, you can open a corporate account as a non-resident, although the process involves much more rigorous compliance checks. Banks usually categorize non-resident applications as high-risk, requiring extensive proof of your professional background and business operations in your home country. You’ll still need to visit the UAE physically for the final signature. Corporate bank account opening dubai for non-residents often requires a higher minimum balance to offset the perceived risk to the institution.
How long does the corporate bank account opening process typically take in 2026?
You should expect the process to take between two and four weeks on average. While digital banks might provide an IBAN in as little as seven working days, traditional institutions often require more time for their compliance committees to review complex files. This timeline depends heavily on the accuracy of your initial submission. Delays usually happen during the Request for Information phase if your answers are incomplete or lack supporting evidence.
What are the minimum balance requirements for a business account in the UAE?
Minimum balance requirements depend on the bank and the specific account tier you select. For most standard business accounts, the Monthly Average Balance (MAB) ranges from 10,000 د.إ to 50,000 د.إ. If you opt for premium corporate banking services, this requirement can exceed 100,000 د.إ. Failing to maintain the agreed balance results in monthly penalties. It’s vital to choose a tier that aligns with your monthly working capital to avoid unnecessary fees.
Is it possible to open a UAE corporate account for an offshore company?
It is possible to open an account for an offshore entity, but it’s the most challenging path in UAE banking. Most banks have a very low appetite for offshore structures due to international transparency standards. You’ll need to provide a Certificate of Incumbency and detailed information about the Ultimate Beneficial Owner’s source of wealth. Because of these complexities, many entrepreneurs choose to set up a mainland or free zone entity to simplify their banking journey.
Can a non-resident be the sole signatory on a Dubai corporate bank account?
A non-resident can be the sole signatory, but you’ll face more scrutiny during the KYC process. Banks generally prefer having a resident director or signatory because it demonstrates a stronger local commitment. As a non-resident, you must fly to the UAE to sign the bank’s physical mandates in person. Your personal bank statements from your home country will be closely examined to verify your financial standing and professional history before approval.
What happens if my corporate bank account application is rejected?
If your application is rejected, the first step is to understand the underlying compliance concern. Banks don’t always provide a detailed explanation, but common issues include mismatched business activities or unclear fund sources. A rejection from one bank doesn’t mean you’re blacklisted from the entire system. You can apply at another institution, provided you address the previous gaps. Working with a specialist helps you fix these issues before your next attempt.
Do I need a physical office space to open a business bank account in Dubai?
Most traditional banks require a physical office with a valid Ejari to approve a corporate account. This physical presence provides the bank with a verifiable location for your operations. While some digital banks and specific free zone setups allow for flexi-desk arrangements, this can sometimes limit your access to certain credit facilities or trade finance products. Having a dedicated office space generally makes the corporate bank account opening dubai process much smoother and more predictable.
Are there digital-only corporate banking options available in the UAE?
Yes, the UAE has several digital-first banking platforms that cater specifically to startups and SMEs. These platforms offer faster onboarding and user-friendly interfaces, making them an excellent choice for businesses with straightforward transaction patterns. However, they might not offer the full suite of services found at legacy banks, such as complex letters of credit or large-scale corporate loans. You should evaluate your long-term trade needs before deciding if a digital-only path is sufficient.